Claim Process Explained
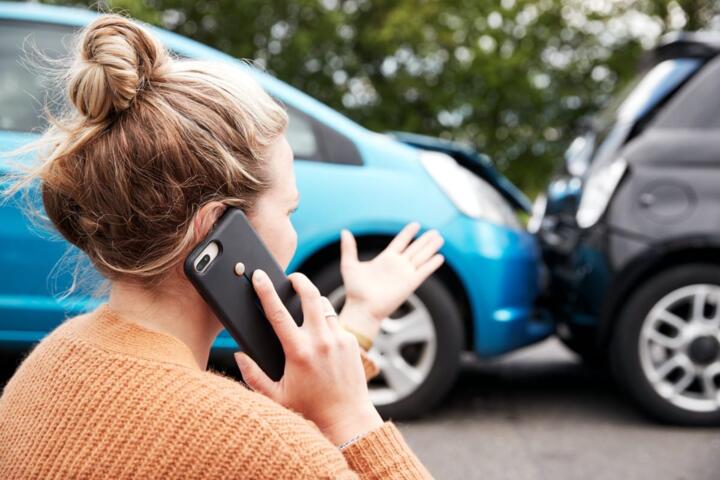
A car crash often triggers immediate stress, but the next steps can shape your recovery financially and legally. Filing a car insurance claim involves notifying your insurer about the incident, detailing the damage, and sometimes proving fault. For example, in 2023, auto insurers handled over 15 million claims involving collision coverage in the United States alone.
After an accident, you capture photos, collect witness statements, and then report to your insurer—usually within 24 to 48 hours. This timeframe varies by company; Geico suggests 24 hours, but State Farm may allow up to 72 hours.
The process cannot move forward without an official claim number. This number acts like your case ID for follow-ups, payments, and disputes.
Expect the insurer to assign an adjuster to assess damages personally or via photos. It is their job to verify costs before approving repairs or payouts.
Timing matters. A delay in filing can reduce benefits or even void coverage, if your policy has prompt notice clauses.
Common Pitfalls
Many people wait too long before filing. The clock isn't just legal—it’s financial. Insurers often require early notification to ensure evidence remains reliable. Ignoring this can mean your insurance company denies the claim, arguing you hindered the investigation.
Another trap: failing to gather enough evidence. Drivers sometimes skip photographing damages or exchanging proper information. This often leads to disputes about fault or repair costs later.
Misunderstanding your coverage is costly. Collision claims will not pay out if you lack collision coverage or if rules such as deductible waivers apply. Around 30% of drivers do not know their policy's exact collision limits or deductibles, per J.D. Power surveys.
Some try to negotiate directly with the other party. Without insurer involvement early, you risk accepting false liability or settling for less than the damage amount.
Last, claiming on the wrong insurer, confusing your comprehensive with collision, or reporting to the insurer of the other driver without your carrier’s knowledge complicates, or sometimes prolongs, claim resolution.
Solutions for Filing Claims
Document the Scene Immediately
Record visible damages, license plates, street signs, and vehicle positions with your phone camera. This visual proof supports your claim against disputes or fraud attempts. Last winter, a neighbor helped me by snapping photos immediately, which made a big difference dealing with the insurance adjuster later.
Exchange All Required Details
Gather driver's names, insurance policies, contact numbers, and vehicle registration. In some states, sharing your insurance card and vehicle registration is legally mandatory. Keeping a small envelope or an app like “MyCarDocs” helps store this info handy.
Notify Your Insurer Without Delay
Call or use the insurer’s app; many companies online offer instant claim submission. Travelers’ mobile app claims module even auto-generates accident forms using GPS and photos. Submit claim numbers to track progress directly.
Prepare for the Adjuster's Assessment
Expect the adjuster within 3 to 7 business days after filing. Provide access to damaged cars or send photos as required. Appraisers may use tools like Xactimate or CCC ONE to estimate repair costs accurately.
Review Your Policy Details
Check deductibles, coverage limits, and exclusions before committing to decisions. Sometimes, opting for total loss payout over repair is financially wiser. Auto insurers pay around $5,000 per collision claim on average; knowing your max payout guides better choices.
Get Repair Estimates From Trusted Shops
After adjuster approval, obtain 2–3 quotes from reputable body shops. Some insurers partner with direct repair programs (e.g., Allstate’s DRP network) cutting claim delays and cutting cost disputes out. But outside shops might offer higher quality.
File Supplemental Claims If Needed
If extra damage surfaces later, file supplements immediately. Adjusters must approve these or risk leaving you stuck covering repairs out of pocket. A friend of mine missed this step and absorbed a $1,200 cost later.
Use Rental Support Options
If your policy includes rental car coverage, activate it during the claim process. Insurers like Progressive often offer direct billing, saving time and upfront expense.
Track and Follow Up Continuously
Claims can drag if neglected. Check your insurer’s claim portal or call agents weekly. This persistence reduces backlogs and pressures adjusters to meet deadlines.
Real-Life Claim Examples
Company A, a midsize delivery fleet, reported an accident involving three trucks resulting in $40,000 in damages. By promptly submitting claims with detailed photos and authorized repair estimates, they reduced downtime from 15 days average to 7 days. The insurer also approved a rental contract faster, keeping business on schedule.
Individual driver Sara filed a claim with State Farm after a rear-end collision on Route 95. She used the company's mobile app to upload documentation, then contacted two local repair shops for quotes. By comparing, she avoided an $800 potential overcharge, and the repair completed in 4 days—down from the usual 10-day estimate she experienced years ago.
List to File Successfully
| Step | Action | Purpose | Tool/Tip |
|---|---|---|---|
| 1 | Take photos immediately | Document damage and scene | Smartphone camera |
| 2 | Exchange info | Identify parties involved | Insurance cards, apps |
| 3 | Report to insurer fast | Start claim process | Company apps, phone |
| 4 | Prepare for inspection | Verify damages | Adjuster visit, photos |
| 5 | Compare repair quotes | Avoid overspending | Local shops, DRP |
Errors to Avoid
Waiting too long is the biggest blunder. Claims can become tangled or denied past deadlines. Another is under-reporting damage; minor cracks often hide more serious issues that worsen later and spike costs.
Avoid admitting fault at the scene. State facts only and let insurers decide liability. Early guilt acknowledgments risk payout reductions.
Failure to update insurers about medical issues post-accident can lead to denied injury claims. Medical reports within two weeks capture conditions accurately.
Ignoring your policy’s small print chapters — such as exclusions or claim limits — causes frustration later when expected payouts fall short.
FAQ
How soon must I file my claim?
Most insurers require notice within 24 to 72 hours, but consult your policy as this varies widely.
Can I repair my car before the insurer inspects it?
Not advisable. Insurers want to assess damage first; premature repairs can complicate claims.
What if the other driver has no insurance?
Your uninsured motorist coverage covers such cases but confirm if your policy includes it.
Does filing a claim increase my premium?
It depends on your insurer and claim history; one claim may not raise rates, but multiple claims often do.
How do I appeal if my claim is denied?
Gather additional evidence and formally request a review or consider consulting a public adjuster or attorney.
Author's Insight
Having managed dozens of auto claims, I’ve seen how documenting everything at the scene accelerates payouts dramatically. Once, a client’s careful photo logs trimmed his claim process by a week. Clear communication with insurers—never assuming they know every detail—avoids many pitfalls. Claims are sometimes a waiting game, but active follow-up? That’s your best tool.
Key Points
File a claim swiftly by documenting accident details and contacting your insurer within the earliest window. Keep clear records, understand your policy’s nuances, and monitor the process actively. Avoid admitting fault prematurely, and evaluate repair options carefully. Sound preparation shortens delays and reduces your financial exposure.